Retirement Planning in Your 40s and 50s: A Mid-Career Financial Checkup

Retirement planning can feel distant in your 20s and 30s, but by your 40s and 50s the numbers begin to carry more meaning. Careers are often more established, household income may be higher, and there is usually a clearer picture of what you want the next stage of life to look like. At the same time, these years can be financially crowded with college costs, aging parents, mortgages, business obligations, and other competing priorities.

That combination makes mid-career an especially useful time for a financial checkup. The goal is not to determine whether you have reached some universal savings target. It is to understand whether your current direction is likely to support the life you want later and, if not, what adjustments are still realistic while time remains on your side.

Start with the amount you are saving, but do not stop there. Consider where the money is being saved and how those accounts may be taxed in retirement. Traditional retirement accounts, Roth accounts, taxable investments, pensions, business interests, and other assets can produce very different tax results when funds are eventually withdrawn. Having a mix of account types may create more flexibility later, although the right balance depends on your circumstances.

Debt also deserves attention. Carrying a mortgage into retirement is not automatically a mistake, and paying every debt off as quickly as possible is not automatically the best strategy. What matters is how future payments fit with expected retirement income and other priorities. High-interest debt, in particular, can compete directly with long-term savings and may deserve a more aggressive plan.

For many people in their 40s and 50s, retirement planning also intersects with family responsibilities. Helping children with college, supporting adult children, or assisting aging parents can be meaningful choices, but those commitments should be considered alongside your own long-term security. Unlike college, retirement cannot usually be financed with a loan. Protecting your future does not mean refusing to help family; it means understanding what level of support is sustainable.

Business owners face an additional layer of planning. The value of the business may represent a significant part of anticipated retirement resources, but turning that value into spendable retirement income requires a realistic succession or exit plan. Assuming the business will simply be sold at the right time and at the right price can create risk if no preparation has been done.

Your 40s and 50s are not a deadline, but they are an opportunity. There is still meaningful time for savings to grow, for spending habits to change, and for tax and retirement strategies to be refined. A coordinated review with your financial and tax professionals can help you understand where you stand today and which adjustments may have the greatest impact on the years ahead.

Category:

Year-End Tax Planning Starts Earlier Than You Think

September may feel early to start thinking about year-end taxes, but that is exactly why it can be such a useful time to review your financial picture. By the final weeks of December, many decisions have already been made and many opportunities have narrowed. Starting earlier gives you time to evaluate where the year is heading, consider your options, and make thoughtful adjustments rather than rushing to react.

For business owners, the first question is often whether this year's income and expenses are tracking close to expectations. A company that has grown more quickly than anticipated may be facing a different tax picture than it did at the beginning of the year. The same is true for a business that purchased equipment, added employees, changed compensation, or experienced an unusually strong or weak quarter. A review now can help determine whether estimated payments still make sense and whether cash reserves are adequate for upcoming obligations.

Individuals and families can benefit from the same kind of early look. A job change, bonus, investment sale, retirement distribution, new business venture, or significant life event can all affect the amount of tax ultimately due. None of these necessarily creates a problem, but they can make last year's assumptions less useful. The earlier those changes are identified, the more time there is to plan around them.

Retirement contributions are another area worth reviewing before the year becomes hectic. Depending on the type of account and the taxpayer's circumstances, contribution decisions can affect both long-term savings and the current tax picture. Business owners may also want to review retirement plan options for themselves and their employees while there is still time to handle the administrative details properly.

Charitable giving, capital purchases, and the timing of certain income or expenses may also deserve attention. The best choice is highly individual, and a tax deduction should never be the only reason to make a financial decision. The point of planning is to understand the tax consequences before acting, so that tax considerations can be weighed alongside cash flow, business needs, and long-term goals.

An early year-end review is also a good time to make sure records are organized. Waiting until tax season to reconstruct transactions, locate documents, or sort through business expenses can make an already busy period more difficult. A little organization in the fall can make the eventual filing process more accurate and far less stressful.

Year-end tax planning is not about searching for last-minute tricks. It is about looking ahead while there is still enough time to make informed decisions. If your income, business activity, investments, or personal circumstances have changed this year, consider scheduling a planning conversation before the holiday season begins. Your CPA or accountant can help you evaluate the numbers and identify which decisions, if any, are worth making before December 31.

Category:

Overlooked Small Business Tax Deductions

Most missed business deductions are not hidden in an obscure section of the tax code. They are lost in ordinary transactions that were paid from the wrong account, recorded without enough detail, or forgotten by the time the return was prepared. Good documentation is often more valuable than a longer list of possible write-offs.

In general, a deductible business expense must be ordinary and necessary for the trade or business. That does not mean every expense that feels helpful will qualify, and personal costs do not become deductible simply because a business owner paid them. The purpose, business use, and records all matter.

Look Beyond the Largest Expenses

Owners usually remember rent, payroll, inventory, and major equipment. Smaller recurring costs are easier to miss. These may include software subscriptions, cloud storage, website services, payment-processing fees, bank charges, professional dues, business insurance, licenses, continuing education, postage, and modest office supplies.

Professional services are another common gap. Fees paid for accounting, legal work, bookkeeping, payroll administration, business consulting, and certain technology services may be deductible when they relate to the business. Retain invoices that explain the service rather than relying only on a bank statement.

Track Expenses That Require Allocation

Mixed-use expenses need special attention. A vehicle used for both business and personal driving requires records that support the business portion. A phone or internet plan may also need to be allocated. Waiting until tax season to reconstruct mileage or estimate percentages is less reliable than maintaining a contemporaneous log.

A qualifying home office may provide a deduction, but the rules are specific. The space generally must be used regularly and exclusively for business, with additional requirements depending on the situation. A dining table used for work during the day and family meals at night is not the same as a dedicated office.

Travel, meals, gifts, and education can also receive close scrutiny. Record who was involved, the business purpose, the date, and the amount. A receipt alone may show what was purchased, but not why it was connected to the business.

Treat Equipment Purchases Separately

Computers, machinery, furniture, and vehicles may be capital assets rather than routine supplies. Depending on the property and current tax rules, the cost may be recovered through depreciation or an available expensing election. Timing, business-use percentage, financing, and the placed-in-service date can affect the result. Ask your CPA before assuming that a purchase will produce an immediate full deduction.

The easiest way to preserve deductions is to create a monthly close routine. Reconcile bank and credit-card accounts, categorize uncoded transactions, attach digital receipts, update mileage, and note the business purpose while the details are fresh. Separate business accounts and cards make the process much easier.

A tax deduction should follow a sound business decision, not drive it. Before making a large purchase or taking an aggressive position, review the facts with your tax professional. The goal is to claim every legitimate deduction while keeping records strong enough to support the return.

Category:

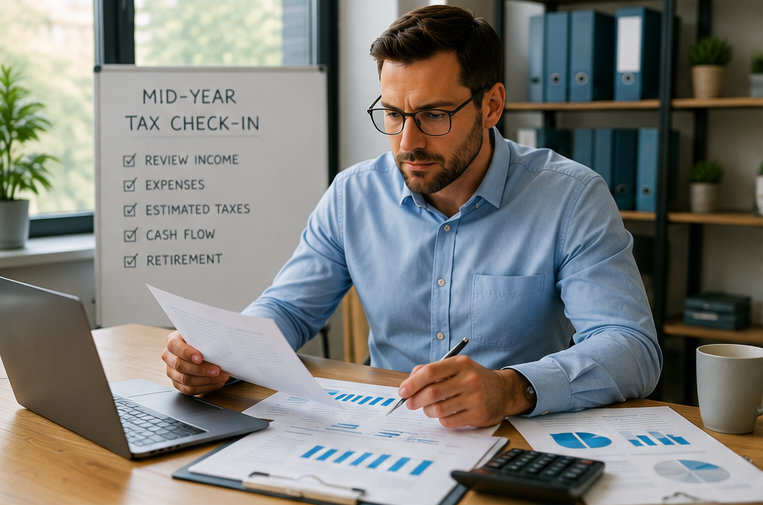
Mid-Year Tax Check-In for Business Owners

Mid-year tax reviews provide business owners with an opportunity to reassess financial assumptions before year-end decisions become time-sensitive. Revenue, expenses, and profitability often shift throughout the year, and waiting until tax season to evaluate those changes can limit planning options.

A review during the middle of the year allows businesses to evaluate estimated tax payments, cash reserves, equipment purchases, and retirement contribution opportunities while there is still time to adjust strategy. It also provides visibility into broader operational trends that may influence long-term planning.

For many business owners, the value of a mid-year review is less about reacting to problems and more about maintaining clarity. Small adjustments made proactively are generally easier and more effective than large corrections made later.

The goal is not unnecessary complexity, but greater confidence in the decisions being made throughout the remainder of the year.

Category:

A Better Way to Budget for Taxes as a Business Owner

Running a business requires making ongoing financial decisions grounded in a clear understanding of available resources. Taxes are often treated as a separate obligation, addressed only when deadlines approach. This can create unnecessary pressure and disrupt otherwise stable cash flow.

A more effective approach is to incorporate tax planning into your regular financial processes. Rather than viewing revenue as fully available, it is helpful to recognize that a portion is already committed. This perspective allows for better decisions throughout the year and reduces the likelihood of unexpected obligations.

Setting aside a consistent percentage of income as it is received is one of the most practical ways to create stability. While the exact percentage varies, consistency ensures funds are available when needed and reduces the impact of quarterly payments.

Maintaining a separate account for tax reserves can further improve clarity. It provides a clear distinction between operating capital and tax obligations and helps prevent funds from being used unintentionally.

It is also important to periodically reassess your assumptions. Changes in revenue, expenses, or deductions can alter your tax position. A mid-year review allows for adjustments before year-end and helps avoid surprises.

Ultimately, the objective is not to eliminate complexity but to manage it effectively. When tax planning becomes part of your routine, it supports better decision-making and contributes to the overall stability of the business.


Category:

Income Volatility and Tax Planning: Strategies for High Earners, Entrepreneurs, and Commission-Based Professionals

Most tax advice is written for people with predictable paychecks. Same employer, same withholding, same general ballpark every single year. File in April, maybe get a refund, move on. That framework doesn't map onto the financial reality of high earners, entrepreneurs, or commission-based professionals whose income swings significantly from one quarter to the next, or one year to the next.

For those people, tax planning isn't a once-a-year exercise. It's an active, ongoing process that requires thinking several moves ahead. The good news is that variable income, managed well, opens up planning opportunities that a steady W-2 earner rarely gets access to. A CPA who works with variable-income clients regularly knows exactly how to find those windows and use them.

Variable Income Creates Unique Tax Exposure

When income fluctuates, the tax consequences fluctuate with it. A commission-based sales professional who earns $80,000 in one year and $210,000 the next isn't just dealing with more money in year two. They're potentially jumping multiple tax brackets, triggering different phase-out thresholds for deductions and credits, and facing a substantially higher tax bill they may not have planned for.

Entrepreneurs face a version of this constantly. A strong product launch, a single large contract, or a business sale can push taxable income into territory that feels foreign compared to the prior year. Without a plan in place before that income arrives, the resulting tax liability can feel like a gut punch in April.

The goal of smart tax planning for variable earners isn't to avoid taxes. It's to avoid surprises, smooth out liability across years where possible, and capture every legitimate strategy available.

Estimated Taxes Deserve Serious Attention

For anyone without standard payroll withholding covering their full tax obligation, estimated quarterly tax payments are the mechanism that keeps the IRS satisfied throughout the year. Missing them, or underpaying significantly, leads to penalties that add up faster than most people expect.

The challenge with variable income is that estimating accurately is genuinely difficult. The IRS offers two safe harbor options that help. Paying 100% of the prior year's tax liability, or 110% for higher earners, protects against underpayment penalties even if the current year turns out to be significantly bigger. The other option is paying 90% of the actual current-year liability, which requires a reasonably accurate projection of what the year will produce.

A CPA can run those projections, track income as the year develops, and adjust estimated payments each quarter to reflect what's actually happening rather than what was guessed back in January.

Retirement Accounts Absorb Income in High-Earning Years

One of the most powerful tools available to entrepreneurs and self-employed professionals is the ability to contribute substantially more to retirement accounts than a standard employee can. A SEP-IRA allows contributions up to 25% of net self-employment income, with a current cap well above what a traditional IRA permits. A Solo 401(k) pushes the ceiling even higher by combining employee and employer contribution limits into a single account.

In a high-income year, maxing out retirement contributions does two things simultaneously. It builds long-term wealth and reduces taxable income in the same motion. For someone sitting at $350,000 in net income, moving $60,000 or more into a retirement account before year-end isn't just good savings practice. It's a tax strategy with immediate, measurable impact on the current year's liability.

The window for making those contributions has hard deadlines. Working with a CPA well before year-end ensures those opportunities don't expire unused.

Timing Income and Expenses Strategically Pays Off

Variable earners have something salaried employees generally don't: some degree of control over when income gets recognized and when expenses get paid. An entrepreneur who's had an exceptionally strong year might push the billing date on a December project into January, shifting that income into the following tax year. A commission professional who knows a big deal is closing might accelerate deductible expenses before December 31st to offset some of the income hitting that year.

These moves require planning ahead rather than reacting after the fact. Expenses paid in January don't help a December tax bill. Income already received can't be un-received. The further in advance a variable earner is thinking about these decisions, the more flexibility they actually have to act on them.

Loss Years Carry Forward Into Profitable Ones

Not every year is a strong one. Entrepreneurs especially go through stretches where expenses outpace revenue, and those net operating losses don't have to disappear. Under current tax rules, net operating losses can be carried forward to offset income in future profitable years, up to 80% of taxable income in the carryforward year.

For a business owner who had a rough year followed by a strong one, that carryforward can meaningfully reduce the tax bill in the recovery year. Tracking those losses properly, and applying them at the right time, is exactly the kind of detail a CPA manages that a variable earner doing their own taxes might miss entirely.

Bunching Deductions Produces Bigger Results

The standard deduction is substantial enough that many taxpayers don't benefit from itemizing in any given year. For variable earners who have some control over timing, bunching deductible expenses into a single tax year rather than spreading them evenly can push total deductions above the standard deduction threshold and produce a larger combined benefit over a two-year window.

Charitable contributions are the most flexible tool for this strategy. Donor-advised funds let a taxpayer make a large contribution in one year, claim the full deduction immediately, and then distribute grants to chosen charities over multiple years on their own timeline.

Variable income doesn't have to mean variable tax outcomes. With the right planning structure in place, high earners, entrepreneurs, and commission-based professionals can approach even their biggest income years with a clear strategy rather than a stack of surprises waiting in April. The strategies exist. The timing matters enormously. Reaching out to a CPA before the year closes, or better yet at the start of one, is where that planning actually begins.


by Kate Supino
 

Category:

How Does Tax Return Fraud Happen?

Nobody wants to think about criminals rifling through their financial life, but tax return fraud has turned into one of the biggest headaches facing American taxpayers. The IRS flagged over a million returns for possible identity theft back in 2023 alone—returns worth roughly $6.3 billion in fraudulent refunds. Those numbers keep climbing.

The whole scheme runs on stolen Social Security numbers. A thief gets someone's SSN from a data breach, a phishing scam, or a crooked employee at a medical office. That nine-digit number is really all they need. With a Social Security number and basic biographical details scraped from public records, a criminal can slap together a tax return and file it before the real taxpayer even thinks about gathering their W-2s.

The fraudulent return typically claims a refund. Sometimes a modest one, sometimes wildly inflated with invented income and fake withholdings. The criminal directs that refund to a prepaid debit card or a bank account they control. Money hits the account, they drain it, and they move on to the next victim.

Legitimate taxpayers discover the problem when they sit down to file and the IRS rejects their return. The system already shows a filing under that Social Security number. Suddenly an ordinary person finds themselves tangled in a bureaucratic mess that, according to the Taxpayer Advocate Service, takes an average of nineteen months to sort out.

The Timing Gap That Criminals Love

Tax season opens in mid-January. Employers have until late March to submit wage information to the IRS. That window—roughly ten weeks—gives fraudsters room to operate. They file fast, grab refunds, and vanish before the IRS receives the data needed to verify anything. The agency has tightened its filters over the years, catching more suspicious returns before refunds go out, but criminals adapt just as quickly.

Stolen Data Comes From Everywhere

Data breaches at major corporations have dumped hundreds of millions of Social Security numbers onto black markets. Healthcare systems, retailers, credit bureaus, government agencies—the list of compromised organizations grows yearly. But high-tech hacking isn't the only source.

Phishing remains disturbingly effective. Emails and texts dressed up to look like official IRS communications trick people into handing over personal information. The messages warn about unpaid taxes or promise refunds, creating enough panic that recipients click links and enter sensitive data without thinking.

Children make attractive targets too. Their Social Security numbers sit unused for years. Criminals buy infant SSNs on dark web marketplaces and file fraudulent returns knowing nobody will notice until that child grows up and applies for student loans. Parents rarely check whether someone filed taxes using their eight-year-old's identity.

Business Identity Theft Happens Too

Fraudsters don't limit themselves to individual returns. Stealing or fabricating Employer Identification Numbers allows criminals to file business tax returns claiming substantial refunds. Business taxation runs complicated enough that these schemes sometimes escape detection longer than individual fraud cases.

Criminals behind business identity theft often create fictitious employees or inflate deductions to generate large refund claims. Some schemes involve filing amended returns for prior years, banking on the fact that businesses may not monitor correspondence about tax years they consider closed.

Social Media Scams Keep Evolving

A newer twist involves bad tax advice spreading across social media platforms. Influencers promote supposed loopholes or secret credits the IRS doesn't want people knowing about. Some schemes encourage filing for credits that don't exist or that the filer clearly doesn't qualify for—things like fuel tax credits claimed by people who don't own farms or commercial vehicles.

The IRS has cracked down hard on fraudulent claims, but viral misinformation spreads faster than corrections. Taxpayers who follow this advice face audits, penalties, and demands to repay refunds they never should have received.

The IRS Identity Protection PIN Makes a Real Difference

The IRS assigns something called an Identity Protection PIN to confirmed victims of tax-related identity theft. Once a case gets resolved, the agency automatically mails a CP01A notice each January containing a new six-digit IP PIN for that year. The number works like a password—when someone files a return using that Social Security number, the IRS checks whether the correct IP PIN accompanies it. Wrong number or missing number means the return gets rejected.

Criminals who have stolen a Social Security number cannot file successfully without also having the current year's IP PIN. The IRS generates fresh PINs annually, so even if a thief somehow obtained last year's number, it becomes worthless come January.

Taxpayers who haven't been victimized can also voluntarily opt into the program through their IRS online account. The protection works the same either way—anyone trying to file a fraudulent return hits a wall without that six-digit code.

Basic Precautions Matter

Filing early cuts off the window criminals rely on. A return already in the system blocks any subsequent filing attempt. Strong passwords on tax software accounts prevent unauthorized access. Shredding documents before throwing them away keeps dumpster divers empty-handed.

Any unsolicited contact claiming to come from the IRS deserves heavy skepticism. The agency sends letters through postal mail—not phone calls demanding immediate payment or emails requesting personal data.

Businesses need written security plans covering client data storage and protection. The IRS requires professional preparers to maintain these safeguards.

Victims Face a Long Road

Someone who discovers fraud on their account needs to file a paper return along with Form 14039, the Identity Theft Affidavit. The IRS assigns these cases to a specialized unit, but resolution takes time—often well over a year. Beyond the delayed refund, victims frequently discover broader identity compromise requiring credit freezes and ongoing monitoring.

Tax return fraud shows no signs of slowing down, unfortunately. Criminals keep refining their methods while stolen data circulates freely online. Protective steps taken now—especially the IP PIN program—keep taxpayers from becoming easy marks in a system where easy marks get hit first. Contact your CPA today to learn more about protecting your tax return.


by Kate Supino


Category:

Why Sales Tax Rules Challenge Growing Small Business Owners

Sales tax seemed pretty manageable when you first opened your doors. You had local customers, one state to deal with, and the whole process took maybe an hour each month. Fast forward a couple years, and you're probably wondering how something so simple turned into such a mess.

If your business has expanded beyond your immediate area, you've learned the hard way that sales tax gets complicated in a hurry. The system that worked fine for your hometown shop falls apart once you start reaching customers in other places.

Each State Runs Its Own Show

There isn't a national sales tax system in America. Every state gets to make up its own rules about rates, what's taxable, and when businesses need to collect. Five states skip sales tax entirely. The other 45 states? They've all gone their own direction.

You can't assume anything transfers from one state to another. That sweater you sell might be tax-exempt in Pennsylvania but fully taxable in Texas. Software subscriptions could be taxable in one state and completely ignored in the next state over. Food, services, digital products... the rules bounce all over the place depending on where your customer lives.

Business owners can spend entire afternoons just trying to figure out if their product is taxable in a single state. Multiply that research across ten states and you can see why this becomes such a drain on your time.

Nobody Told You About Economic Nexus

Ten years ago, sales tax was pretty straightforward. You only had to worry about states where you had a physical location. Rent an office or warehouse somewhere, and you'd collect tax there. No physical presence meant no tax obligation.

That changed completely in 2018 when the Supreme Court decided that physical presence didn't have to be the standard anymore. States jumped on this immediately. Now most of them say you owe tax based purely on how much you sell there, regardless of whether you've ever visited. It’s called nexus.

The typical threshold is $100,000 in sales or 200 separate transactions per year. Hit either number in a state, and congratulations, you've got a new tax obligation. Your thriving online store just created paperwork in states you've never even thought about.

These thresholds aren't even consistent. Colorado might use one standard while Tennessee uses another. You've got to track your sales separately for each state and figure out when you cross their particular line. It's tedious work that nobody enjoys.

Setting Up in New States Eats Up Your Schedule

Discovering you have a nexus somewhere is just the beginning. Before you can legally collect tax, you need to register with that state's revenue department. Sounds quick, right? It usually isn't.

Every state designed its own registration system. One state wants a simple online form. Another state requires notarized documents. A third state takes six weeks to process your application. Some charge fees. Others want security deposits if you're in certain industries.

Then you've got to sort out the actual rates. City taxes, county taxes, special district taxes... they all stack up differently depending on exactly where your customer is located. The rate on Main Street might be different from the rate on Oak Avenue two blocks over. Calculate wrong and you're either ripping off your customers or shorting the state.

Software Solves Some Problems But Not All

Plenty of business owners eventually buy sales tax software to handle the calculations. These programs can be lifesavers. They figure out the right rate for each sale and file your returns automatically. For businesses doing volume across multiple states, they're often essential.

But software won't solve everything. You still have to figure out where you've got nexus. You still have to register in those places before the software can do anything. You still need to keep watching your sales numbers to catch when you trigger obligations in new states.

The pricing can sting too. Most platforms charge based on how many transactions you process or how many states you're operating in. A growing business can rack up substantial monthly fees. You'll need to decide if that cost beats the alternative of handling everything yourself and potentially making expensive mistakes.

Filing Returns Becomes a Calendar Nightmare

Once you're registered somewhere, that state expects regular tax returns. How often depends on your sales volume there. High-volume states might want monthly filings. Low-volume states might only require annual returns. Medium volume? That's probably quarterly.

Keeping all these deadlines straight gets ridiculous. You might have three states due on the 20th, two states due on the last day of the month, and one state with a weird deadline on the 23rd. Miss any of them and penalties start piling up immediately, even if you didn't actually owe any tax.

Some states require "zero returns" when you haven't made any sales there. You still have to file paperwork saying you have nothing to report. Skip it and you'll get penalty notices.

What started as managing one monthly return in your home state can easily become juggling fifteen different filings throughout the year. Every one of them needs attention.

Bringing in Professional Help

Most small business owners eventually hit a point where they realize sales tax management is eating too much of their time. The rules shift constantly, vary wildly between states, and come with real financial risks if you mess them up.

A CPA who knows sales tax can take this entire headache off your plate. They'll figure out where you need to be registered, handle the paperwork, make sure you're charging customers correctly, and keep all your filings on schedule. They also stay on top of rule changes so you don't get blindsided by new requirements.

Think about what your time is worth. Those hours you spend researching tax rules in different states could go toward actually running your business. Sometimes the smartest move is admitting you need someone who does this stuff all day, every day. Contact your CPA for help.

by Kate Supino


Category:

Understanding Estimated Taxes: A Guide for Self-Employed Individuals

Self-employment offers flexibility, independence and the potential for unlimited earnings, but it also comes with important financial responsibilities—one of the most significant being taxes, as your CPA can attest to. Unlike traditional employees who have taxes withheld from their paychecks, self-employed individuals must handle their own tax obligations, including making estimated tax payments throughout the year. Failing to do so can lead to underpayment penalties, interest charges, and financial stress when tax season arrives. Understanding how estimated taxes work, how to calculate them, and when to pay them is essential for staying compliant with IRS rules and avoiding unnecessary costs.

What Are Estimated Taxes?

Estimated taxes are payments made to the IRS on a quarterly basis. These payments cover income tax and self-employment tax, which includes Social Security and Medicare contributions. Since self-employed individuals do not have taxes automatically withheld from their earnings, they must estimate their tax liability and make payments to the IRS throughout the year. The purpose of estimated taxes is to ensure that individuals prepay a sufficient amount of their tax liability rather than waiting until tax season, when a large bill could come due.

Generally, self-employed individuals, freelancers, independent contractors and business owners who expect to owe at least $1,000 in taxes after subtracting any withholding or credits must make estimated tax payments. This applies to income from various sources, including contract work, small business earnings, rental properties, and investments. Even individuals with side businesses or gig work may need to pay estimated taxes if their earnings push their tax liability over the threshold.

Calculating Estimated Tax Payments

To determine how much to pay in estimated taxes, self-employed individuals must first estimate their total taxable income for the year, taking into account business expenses, deductions, and any available tax credits. The IRS provides Form 1040-ES, which includes a worksheet to help calculate estimated taxes. The key components of this calculation include:

  • Income tax - Based on the expected taxable income after deductions.

  • Self-employment tax - This tax covers Social Security and Medicare contributions, amounting to 15.3% of net earnings—12.4% for Social Security and 2.9% for Medicare.

  • Other applicable taxes - Some individuals may owe additional taxes, such as the Net Investment Income Tax.

Because self-employment income can fluctuate throughout the year, it’s advisable to reassess estimated tax calculations regularly. If income increases or decreases significantly, adjustments to estimated payments may be necessary to avoid overpaying or underpaying. Your CPA can help with this.

When and How to Pay Estimated Taxes

The IRS requires estimated taxes to be paid in four installments throughout the year. The typical due dates for these payments are:

  • April 15, covering income earned from January 1 to March 31

  • June 15, covering income earned from April 1 to May 31

  • September 15, covering income earned from June 1 to August 31

  • January 15 of the following year, covering income earned from September 1 to December 31

If the due date falls on a weekend or holiday, the deadline is extended to the next business day. Missing these deadlines can result in penalties and interest charges, so it is crucial to track them carefully.

Estimated tax payments can be made in several ways. The easiest is to have your CPA take care of it.

Avoiding Underpayment Penalties

Failing to pay estimated taxes or underpaying throughout the year can result in IRS penalties, which are calculated based on the amount underpaid and the length of time it remains unpaid. To avoid penalties, individuals should:

  • Make timely and accurate quarterly payments rather than waiting to make a lump sum payment at year-end.

  • Use the safe harbor rule to ensure they pay enough to avoid penalties.

  • Adjust estimated payments if income changes significantly throughout the year.

The IRS may waive penalties in cases of unusual circumstances, such as natural disasters or serious medical emergencies. However, relying on such exceptions is risky, and proper tax planning is always the best approach.

Maximizing Deductions and Reducing Tax Liability

Self-employed individuals have access to several tax deductions that can reduce their taxable income and lower their estimated tax payments. Some of the most common deductions include:

  • Self-employment tax deduction - While self-employed individuals must pay the full self-employment tax, they can deduct half of it as an adjustment to income.

  • Home office deduction - Those who use a dedicated space in their home for business purposes can deduct a portion of their rent, utilities, and other expenses.

  • Business expenses - Ordinary and necessary business expenses, such as office supplies, travel costs, and professional services, are deductible.

  • Health insurance premiums - Self-employed individuals who pay for their own health insurance may be able to deduct their premiums.

  • Retirement contributions - Contributions to SEP IRAs, SIMPLE IRAs, and solo 401(k) plans may be tax-deductible, reducing taxable income while helping build long-term savings.

Tracking deductible expenses throughout the year is essential for accurate tax reporting and maximizing tax savings. Keeping organized records of receipts, invoices, and bank statements can make tax preparation much easier.

Planning for Estimated Taxes and Financial Stability

One of the best strategies for handling estimated taxes is proactive financial planning. Setting aside a percentage of each payment received for taxes can prevent cash flow issues when quarterly payments are due. Many financial professionals recommend saving 25–30% of self-employment income for taxes, though the exact percentage depends on individual circumstances.

Using accounting software or working with a CPA can also simplify estimated tax calculations and ensure compliance. A CPA can help with tax planning, identify potential deductions, and adjust estimated tax payments as needed. By taking a strategic approach to estimated taxes, self-employed individuals can avoid surprises at tax time and maintain financial stability throughout the year.

Estimated taxes are an important part of tax compliance for self-employed individuals, independent contractors, and small business owners. Understanding how to calculate estimated taxes, when to pay them, and how to minimize tax liability can help avoid IRS penalties and financial stress. By making timely payments, keeping accurate records and working with a CPA, self-employed individuals can manage their tax obligations effectively and focus on growing their businesses.

by Kate Supino


Category:

Are You Paying Your Employees Enough? Avoiding Red Flags With Payroll Taxes

Managing payroll is one of the most important responsibilities for business owners. Ensuring employees are paid correctly and on time is essential not only for maintaining morale and compliance but also for avoiding payroll tax issues that could lead to audits, penalties, or even legal trouble. The IRS and state tax agencies pay close attention to payroll taxes, and mistakes—whether intentional or accidental—can trigger red flags that invite unwanted scrutiny.

The Importance of Payroll Compliance

Failing to comply with payroll tax regulations can result in serious consequences. The IRS considers unpaid payroll taxes a major offense since these funds are technically held in trust for employees. Business owners who mismanage payroll taxes may face fines, interest charges, and even criminal liability in severe cases. State agencies can also impose penalties, particularly if unemployment insurance contributions or state income tax withholdings are mishandled.

Common Payroll Tax Red Flags

Certain payroll practices can attract the attention of the IRS and state tax agencies. One of the biggest red flags is misclassifying employees as independent contractors. Employers do not have to withhold taxes for independent contractors, making this classification financially appealing. However, if a worker meets the legal definition of an employee—such as being subject to company control over their work schedule, tools, or job responsibilities—the IRS expects proper tax withholdings. Misclassification can result in back taxes, penalties, and interest.

Another common red flag is failing to deposit payroll taxes on time. The IRS has strict deadlines for payroll tax deposits, and missing these deadlines can lead to automatic penalties. The agency uses an electronic tracking system that quickly identifies late or missing payments. Employers who repeatedly delay payroll tax deposits may trigger an audit or further enforcement action.

Underreporting wages is another issue that can raise concerns. Some businesses may attempt to lower their tax burden by paying employees off the books, reducing reported wages, or providing cash payments without proper documentation. These practices are illegal and can result in severe penalties. The IRS compares wage reports with tax filings, and any discrepancies can lead to further investigation.

Payroll tax discrepancies between federal and state filings can also be problematic. If state unemployment insurance filings do not match federal payroll tax reports, state agencies may flag the discrepancy and conduct an audit. Consistency in reporting across all levels of taxation is critical for avoiding unnecessary scrutiny.

A final red flag involves excessive deductions from employee paychecks. While certain deductions, such as health insurance premiums and retirement contributions, are legitimate, excessive or unauthorized deductions can lead to wage disputes and regulatory investigations. Employees have rights under federal and state labor laws, and improper deductions can result in fines and legal claims against the business.

Best Practices for Payroll Tax Compliance

To avoid payroll tax issues, business owners should implement best practices that ensure compliance and minimize risk. One of the most effective strategies is to properly classify workers from the outset. Reviewing IRS guidelines for determining employee versus independent contractor status can help prevent misclassification errors. If there is any uncertainty, consulting with a CPA is advisable.

Maintaining accurate payroll records is another crucial step. Employers should keep detailed documentation of hours worked, wages paid, tax withholdings, and deductions. Payroll records should be retained for at least four years in case of audits or disputes. 

Timely payroll tax deposits are essential for compliance. Employers should familiarize themselves with deposit schedules and ensure funds are remitted on time, or hire a CPA to take care of it.

Accurate reporting across all tax filings is another important practice. Ensuring that payroll tax forms, such as Form 941 for federal payroll taxes and state unemployment tax filings, align with business tax returns can prevent discrepancies that might raise red flags. Regularly reviewing payroll reports before submission can catch errors before they become a problem.

Regular payroll audits can also help identify and address potential issues before they escalate. Businesses should periodically review payroll practices to ensure compliance with wage laws, tax regulations, and reporting requirements. Internal audits can uncover discrepancies, allowing corrections before regulatory agencies intervene.

Employers should also stay informed about federal and state wage laws. Minimum wage requirements, overtime rules, and tax regulations can change, and failure to comply with new laws can result in fines or lawsuits. Keeping up to date with employment law changes and consulting with a CPA when needed can help ensure ongoing compliance.

The Risks of Ignoring Payroll Tax Compliance

Ignoring payroll tax obligations can have serious financial and legal consequences. The IRS has broad enforcement powers when it comes to payroll tax violations. One of the most severe penalties is the Trust Fund Recovery Penalty (TFRP), which holds business owners personally liable for unpaid payroll taxes. This means that even if a business entity dissolves, the IRS can pursue owners and responsible parties to recover unpaid amounts.

State agencies can also impose penalties for payroll tax violations. Businesses that fail to pay unemployment insurance taxes, for example, may face penalties that increase over time. Additionally, employee wage disputes can lead to lawsuits, and businesses found guilty of wage violations may be required to pay back wages, damages, and attorney fees.

Payroll tax compliance isn’t just a legal requirement—it’s a fundamental aspect of running a responsible and successful business. Paying employees correctly, withholding and remitting taxes on time, and maintaining accurate payroll records are critical for avoiding red flags that could lead to audits or penalties.

By following best practices such as properly classifying workers, making timely tax deposits, and keeping accurate records, business owners can minimize risk and ensure compliance. Regular payroll audits and staying informed about wage laws further strengthen a company’s ability to avoid payroll tax pitfalls.

Rather than viewing payroll taxes as a burden, business owners should see them as part of a well-structured financial system that protects employees and businesses alike.


by Kate Supino


Category:

Industry-Leading Affordability and Value at Every Level

See All Features Buy Now